Blog
Allocate an agent budget by the work people can use
Fund the next useful unit of work, including the people who must review and use it.
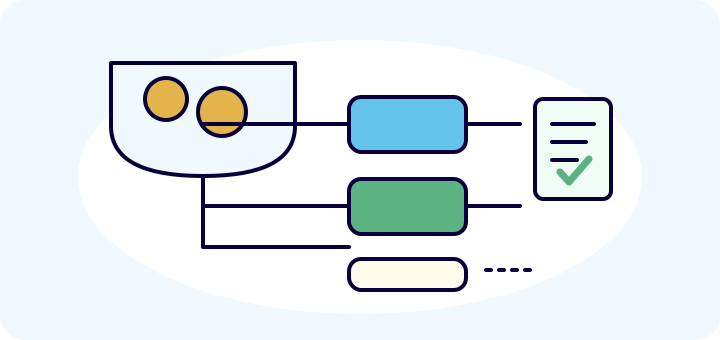
The renewal team wants more account preparation. Sales wants research for a larger prospect list. Marketing wants additional campaign drafts. Each request has a plausible time-saving story, and each team can point to work that is still done manually. A fixed agent budget turns those reasonable requests into a portfolio decision.
Allocate the budget by the next unit of useful work a team can accept, not by an equal share for each department or by the largest projected number of outputs. Compare the incremental service cost, human review burden, evidence of use and consequence of leaving the work undone. Preserve existing commitments before expanding coverage. That approach makes the budget a decision about operating attention rather than a contest between enthusiastic sponsors.
Define the unit before comparing the price
A generated account brief, an accepted account brief and a customer conversation are different units. The first establishes production. The second establishes that someone found the preparation usable. The third may depend on many other conditions. A budget proposal should identify which unit its cost estimate buys and which downstream result remains a hypothesis.
For renewal preparation, the useful unit might be an account owner accepting a dated brief before a scheduled customer discussion. For sales research, it might be a seller accepting a concise account context pack for a named, eligible account. For campaign preparation, it might be a reviewer accepting one concept into the campaign process. Those definitions keep a workflow from looking inexpensive simply because nobody counts the review or the rejected work.
Count service consumption, any separately scoped implementation work and internal review time. Keep these components visible instead of combining everything into a false precision cost. A provider charge can be known while the review estimate is still uncertain. The budget owner should be able to see which assumption needs testing before approval.
Protect the work already promised
Suppose a team has agreed that customer owners will receive preparation for the coming month's scheduled renewal discussions. That is a current operating commitment. Cutting its budget to fund an appealing new prospecting experiment may be sensible, but leadership should explicitly accept the changed commitment. Otherwise a portfolio change appears downstream as a service failure.
Separate the budget into committed work, bounded experiments and unallocated room for variation. These are planning categories, not fixed percentages. A volatile workload may require more room; a stable one may require less. The reserve should have a named decision owner and a release rule, so it does not become an invisible fund available to the loudest request.
The same reasoning applies to human capacity. A manager who can review twelve briefs thoughtfully cannot absorb forty because the generation cost fell. When review becomes the constraint, the next useful investment may be better preparation for twelve accounts rather than more accounts. The existing article on cross-team agent sequencing explains the downstream handoff problem; budget allocation adds the spending decision at that boundary.
Work through the marginal choice
Consider a fictional monthly planning exercise with 1,000 internal budget units. These units are deliberately abstract: they are neither RevTech credits nor a provider price. The team reserves 600 for agreed services and 100 for workload variation. It can allocate the remaining 300 to one expansion or split it among smaller tests.
Sales proposes 100 additional account packs costing 300 units. The receiving sellers can commit to reviewing only 40 this month. Marketing proposes ten additional concepts for the same 300 units, but its existing review queue is already full. Customer success proposes 30 more renewal briefs for 240 units, and the account owners have named the discussions those briefs will support. The remaining 60 could fund a small test of a different sales research scope.
The provisional choice is the renewal expansion plus the sales test. It is not based on a claim that retention is always more valuable than acquisition. It reflects a defined receiving use, feasible review capacity and a smaller uncertainty to resolve. If Sales supplies an accepted plan to use the extra research, the next month's allocation may change. Marketing can use its current capacity to resolve the review queue before asking for more production.
No revenue uplift is assigned to this example. The decision buys prepared work under explicit conditions. Whether that work changes customer outcomes requires a separate observation period and evidence beyond the budget model.
Inspect the acceptance curve
The first accounts in a workflow may be easy to support because their records are complete and their owners are engaged. Expanding to another segment can add missing information, unusual permissions or more complex review. Average cost from the original scope may therefore understate the cost of the next tranche.
Review accepted output in small expansion bands. Ask what changed between the original fifty accounts and the next fifty: source availability, corrections, recipient use or exception handling. This is an acceptance curve, not a universal statistical benchmark. Its purpose is to show where an expansion stops behaving like the original workflow.
For example, a low correction rate in the first band may coexist with poor use in the next. The brief may be accurate but irrelevant to that segment's sales motion. More budget will not fix that mismatch. The owner can narrow the scope, change the prepared output or stop the expansion. Keeping these choices visible makes stopping a useful operating result rather than an embarrassing failure to spend the allocation.
Make value claims at the right level
Recovered time is useful when people can redirect it to work they value. It is not automatically cash saved. A budget case that multiplies every estimated minute by a salary rate and calls the result a financial return skips the question of what actually changes. Include the destination for the capacity and observe whether the old manual step stops.
Business outcomes deserve a separate line. More accepted renewal preparation may help account owners have better conversations; it does not establish that the service caused a retention improvement. A small pilot can show whether the brief was used and how much rework it required before it can support a credible outcome claim.
Use a range for uncertain inputs. If the proposal is attractive only when review takes two minutes and fails when it takes ten, that assumption is the pilot's main question. The smallest useful test measures the uncertain input directly. It does not need a large rollout simply to produce a more impressive activity count.
Give the managed service a concrete budget boundary
RevTech operates fully managed agents within an agreed service scope. Connected data preparation, research, drafting, updates and coordination can support recurring GTM work. The customer retains goals, business rules, permissions, designated reviews and relationships. Budget scope should reflect that division: the service can carry agreed preparation while the revenue leader chooses which preparation deserves attention.
Bring a volume range, an accepted-output definition and a receiving owner to the scoping conversation. Confirm the current capabilities and commercial terms for that work, including how unusual cases and material scope changes are handled. Do not assume that a generic cost model or a demonstration establishes the price or feasibility of a particular workflow.
At the next allocation review, ask each owner to bring one accepted output, one rejected output and one example of what the recipient did next. Pair those examples with the actual cost and review burden. That gives the CRO a practical choice: maintain a useful commitment, expand a proven unit of work, change a weak assumption or fund a different job. The budget then follows work the business can use.
Put the framework to work
Explore the operating model.
Map the work before allocating capacity
Define recurring work, exceptions and human judgment.
ExploreSequence agents across revenue teams
Inspect who receives the added work.
ExploreShow what the capacity was spent on
Separate service health from business outcomes.
ExploreModel the operating case
Use your own assumptions and inspect sensitivity.
ExploreKeep reading.
Plan Renewal Capacity Before the Calendar Gets Crowded
Translate renewal dates into the weeks when preparation, customer conversations and commercial reviews need capacity, with a worked planning example.
Read
Reconcile bookings to ARR without losing the exceptions
A useful reconciliation explains each difference and assigns its resolution; it does not force unlike totals to match.
ReadSee how the work gets done.
Explore how agents prepare work across your revenue teams, and how people review it, guide it and decide what happens next. Fictional data. Real product.
Explore the demo