Blog
Two proposals, one purchase: count pipeline once
How should pipeline represent mutually exclusive proposals for the same purchase?
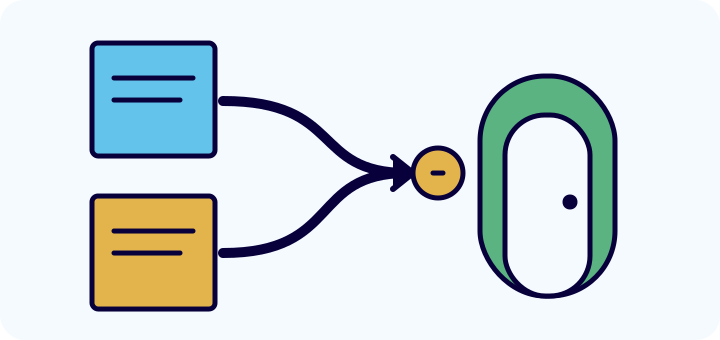
One buyer is considering a regional rollout and a company-wide rollout. The seller creates an opportunity for each option so the team can prepare both proposals. A regional manager counts the smaller deal, an enterprise leader counts the larger one and the company forecast adds them together.
Represent the buyer's purchase decision separately from the proposals offered to satisfy it. If the options are mutually exclusive, preserve them for commercial work but count only the applicable scenario in a given pipeline or forecast view. Separate opportunities are appropriate when purchases are independently possible, not merely because the proposal documents differ.
Establish whether there are one or several decisions
The same account can have genuinely independent projects. Different business units may have separate budgets, outcomes and approval paths. Conversely, two legal entities may be evaluating alternatives within one group purchase. Company identity alone cannot settle whether value is additive.
Ask what would have to be true for both opportunities to close. Could the buyer purchase both scopes without one replacing or incorporating the other? Does each have an independent objective, funding decision and commercial agreement? If the answer is uncertain, retain that uncertainty and avoid presenting the sum as established eligible pipeline.
A shared purchase identifier can be useful even if your CRM does not have a dedicated object for it. Use a supported relationship or governed field that the organization can maintain. The identifier connects alternatives; it should not merge unrelated buying projects simply because they share a sponsor.
Reconcile a fictional book
Consider a fictional pipeline containing a $100,000 regional proposal and a $240,000 company-wide proposal for the same purchase. The wider package includes the region. A separate $60,000 project at the same customer has its own decision and can proceed independently. Another customer's opportunity is $200,000.
Adding every record produces $600,000. Under the current regional scenario, unique proposed commercial value is $360,000: $100,000 plus $60,000 plus $200,000. Under the company-wide alternative it is $500,000. Neither view supports a $600,000 additive total, because the regional scope is already inside the wider option.
The team does not have to pretend the larger possibility is irrelevant. It can show a $360,000 current view and a clearly labelled alternative with $140,000 additional scope. That $140,000 is conditional on a different purchase choice. It is not a second independent deal waiting beside the first.
If the buyer later agrees to purchase the region now and separately evaluate additional regions next year, the structure may change. Record the new evidence, scope and timing before splitting the motion. An internal desire to maintain more pipeline is not evidence of a second purchase.
Preserve the work without preserving the counting error
Do not delete an alternative just because it should not contribute to a total. Its research, proposal history and customer feedback may remain useful. Give it a clear state under the organization's process: alternative under consideration, superseded, independently active or no longer pursued.
Avoid marking an unchosen proposal as an ordinary competitive loss without considering what that means for analysis. If the buyer selected another offer from your company, a loss report should not imply that the whole purchase went to a competitor. The appropriate disposition depends on your definitions, but it should retain the relationship to the selected option.
The same care applies to conversion measures. Creating three proposals for one buying decision and recording one win can produce a misleading opportunity win rate if the metric expects independent buying projects. Fix the record meaning and analytical population together. Do not repair only the current-period sum.
Decide how the forecast selects an alternative
A pipeline view may show the current customer-discussed package, while a forecast uses an approved manager judgment. Name the convention. Do not automatically select the largest amount, the most recent record or the opportunity with the strongest stage label unless that is the approved and defensible rule.
If no option is sufficiently supported, show the unresolved purchase with its alternatives outside the confident subtotal. A manager can still discuss the opportunity. The arithmetic should not force a level of certainty the buyer has not supplied.
When the selected option changes, explain the movement as a scope substitution. In the fictional example, replacing the regional view with the company-wide view adds $140,000, not a fresh $240,000 on top of an unchanged $100,000. Preserve the prior view so the next forecast bridge can show what actually changed.
Make the customer story visible to everyone preparing work
Proposal alternatives can also create duplicate research, conflicting messages and unclear ownership. Give the account team one coordinated customer plan and show which proposal is current. The seller should not discover a second active sequence because another team sees an apparently separate opportunity.
RevTech's Customer Context brings connected account, people and opportunity information into prepared work. Confirm how your actual purchase relationships and exclusions will be represented; the platform description does not guarantee automatic detection of every alternative proposal. Your team decides the commercial identity and reporting policy.
Start by inspecting the largest accounts with multiple open opportunities. Ask whether each amount could become an independent purchase. That question can improve the pipeline explanation and the buyer's experience without removing legitimate commercial options from the team's view.
Sources and scope
Original pipeline-counting method and fictional arithmetic, reviewed October 30, 2026. Current RevTech Customer Context supports the limited preparation description. The existing account-hierarchy article supplies the related distinction between corporate structure and buying authority.
Put the framework to work
Explore the operating model.
Account Hierarchy and Buying Authority
Map account relationships and buying authority before deciding how opportunities belong together.
ExploreGTM Context Graph
Explore the shared account, contact and opportunity context behind revenue work.
ExploreAI for RevOps | Managed Revenue Operations AI
Explore managed inspections, evidence-backed exceptions and reviewable corrections for RevOps.
Explore
See how the work gets done.
Explore how agents prepare work across your revenue teams, and how people review it, guide it and decide what happens next. Fictional data. Real product.
Explore the demo